S&P 500 Price Prediction: History Points Higher, But October Breadth Is Flashing a Warning

The S&P 500 is entering a seasonally important stretch with two very different historical signals pulling in opposite directions.
On one side, Bull Theory points to a powerful post-midterm election pattern: the S&P 500 has historically performed very well in the 12 months following U.S. midterm elections.
On the other side, The Kobeissi Letter notes that October has historically had the weakest market breadth of any month since 1990, and current breadth is even weaker than the long-term average.
That creates an interesting setup. The long-term cycle argues for a stronger market over the next year, but the short-term internals still look fragile.
What you'll learn 👉
The Post-Midterm Pattern Is Extremely Strong
Bull Theory’s main point is that the year following a U.S. midterm election has historically been one of the strongest periods for the S&P 500.
Since 1950, the index has finished higher over the following 12 months after every midterm election in the dataset.
A separate historical sample going back to 1942 shows the same result for the November-to-June period after midterms: 21 positive outcomes out of 21.
The broader presidential cycle also supports that view.
Year 3 of the four-year presidential cycle has historically been the strongest year, with Fidelity data from 1961 to 2024 putting the average return at around 18.7%.
The reasoning is partly about uncertainty.
HISTORY SAYS THE NEXT 12 MONTHS COULD BE VERY BULLISH FOR S&P500 Since 1950, the S&P 500 has gone up in the 12 months after every single US midterm election. A separate dataset going back to 1942 finds the same thing in the November to June window after a midterm: 21 for 21, also positive every time. Year 3 of the presidential cycle, the year right after the midterm, has also historically been the strongest year of the entire 4-year cycle. Fidelity’s 1961-2024 data puts the average at 18.7%. Here’s why this keeps happening. Before an election, markets have to price every possible outcome at once: who controls Congress, which taxes get cut or raised, which regulations pass or die. Nobody can commit real money when 5 different futures are still live. That’s why midterm years are historically the weakest part of the 4-year cycle, averaging just 3.8% from 1945 to 2025, compared to 10.9% in the other three years, with an 18% average drawdown along the way. Once the result is locked in, that entire range of outcomes collapses into one. Markets don’t need the winner to be market friendly. They just need the unknown removed, and removing the unknown alone lowers the risk premium investors demand to hold stocks. This pattern has survived completely different crises, for completely different reasons, every single cycle: After the 2010 midterms, the US was still digging out of the financial crisis. The Fed launched $600 billion of QE2, buying long term Treasuries to push yields down and force money into riskier assets. It worked, until 2011, when the US debt ceiling standoff led to the first-ever downgrade of US credit, and Europe’s sovereign debt crisis exploded at the same time. The S&P fell almost 19% at its worst point that year. It still finished the year positive. After the 2014 midterms, the US economy and labor market looked fine, but oil prices collapsed and the dollar spiked, gutting earnings across the entire energy sector. Then in 2015, China devalued its currency and its economy slowed sharply, triggering a global risk off panic, right as the Fed prepared its first rate hike since 2006. The S&P barely survived, finishing up just 3%, the weakest year in the entire 76 year record. But It still didn’t break the streak. After the 2018 midterms, the Fed had hiked rates 4 times that year and was still shrinking its balance sheet. Trade war fears with China pushed the S&P to the edge of a bear market by Christmas Eve. Then Fed Chair Powell reversed course in early 2019, signaled patience, stopped hiking, and eventually cut rates 3 times. Big tech earnings stayed strong and the US and China moved toward a trade truce. The S&P went on to gain nearly 29% that calendar year. After the 2022 midterms, inflation had just peaked at 9.1%, the Fed was still raising rates, and most of Wall Street was calling for a recession. A cooler than expected inflation report landed right after Election Day, convincing investors the Fed was close to done hiking. Stocks can explode while a central bank is still raising rates, because markets price where policy is heading, not where it sits today. Through 2023, the expected recession never came, the Fed slowed down then paused, and a generative AI boom sent Nvidia and the rest of mega cap tech into one of the biggest rallies in years. Four different decades. Four completely different crises, a debt downgrade, an oil crash, a trade war, and the fastest rate-hiking cycle in 40 years. The S&P 500 closed positive after every single one.
— Bull Theory (@BullTheoryio) October 5, 2026
Before an election, markets have to price several possible outcomes at once: control of Congress, tax policy, spending plans, regulation, and fiscal policy.
Once the election is over, investors have more clarity.
The result does not have to be ideal for stocks. Removing uncertainty alone can reduce the risk premium investors demand.
History Shows the Pattern Can Survive Very Difficult Conditions
Bull Theory also points out that this post-midterm strength has appeared through very different market environments.
After the 2010 midterms, the U.S. was still recovering from the financial crisis and later faced the 2011 debt ceiling crisis and the first downgrade of U.S. sovereign credit.
After the 2014 midterms, oil prices collapsed, the dollar strengthened, and China’s slowdown created a major risk-off episode.
After the 2018 midterms, markets were dealing with Fed tightening and the U.S.-China trade war.
After the 2022 midterms, inflation was still high and the Fed was in the middle of its fastest tightening cycle in decades.
Yet the S&P 500 still ended up positive over the following post-midterm periods.
That is why the historical pattern continues to attract attention.
October Breadth Is a Major Short-Term Problem
The Kobeissi Letter’s data paints a very different picture for the current month.
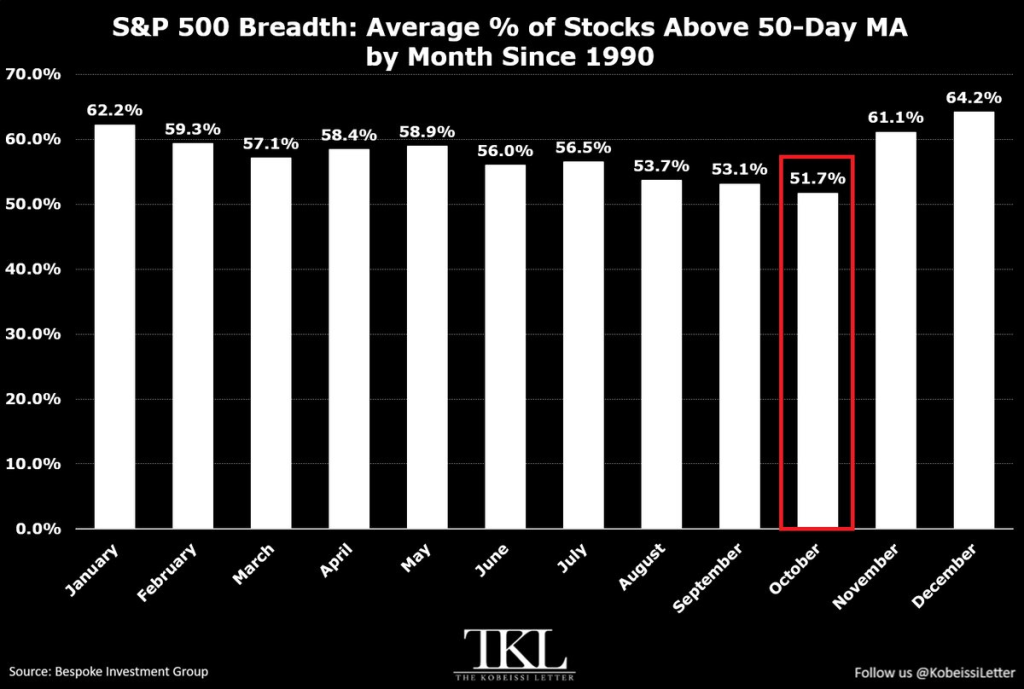
Since 1990, October has had the weakest average market breadth of any month, with only 51.7% of S&P 500 stocks trading above their 50-day moving average.
September is only slightly better at 53.1%.
By comparison, breadth improves substantially later in the year:
- November: 61.1%
- December: 64.2%
- January: 62.2%
The chart makes that seasonal pattern clear.
October stands out as the weakest month, followed by a strong improvement in November and December.
Current Breadth Is Much Worse Than Normal
The bigger concern is that present market breadth is not simply weak by historical standards.
It is extremely weak.
Only about 21.4% of S&P 500 stocks are currently trading above their 50-day moving average, down from roughly 70% in mid-August.
That is far below October’s already weak historical average of 51.7%.
There is another warning sign too: new 52-week lows have outnumbered new highs for 14 consecutive trading days.
That tells us the index may be holding up better than the average stock.
In other words, a relatively small group of large companies may be doing much of the work.
That kind of narrow leadership can continue for some time, but it makes the market more vulnerable if those leaders start losing momentum.
S&P 500 Price Outlook
The two signals can actually fit together.
The short-term setup still looks weak because breadth is poor and October has historically been a difficult month for participation.
That could mean more volatility or another pullback before the market finds a stronger base.
But the longer-term post-midterm pattern remains constructive.
If history repeats again, the weakness in October could end up being part of a transition into a stronger November-to-2027 period.
The key thing to watch is breadth.
If the percentage of stocks above their 50-day moving average starts recovering from the current 21.4% area and moves back toward 50% or higher, that would show the rally is becoming broader and healthier.
If breadth stays depressed and new lows continue dominating, the index could remain vulnerable even if the headline S&P 500 level looks stable.
For more financial news and price predictions, click here.
Subscribe to our YouTube channel for daily crypto updates, market insights, and expert analysis.